Greece’s problem with shifting rules did not begin at this year’s Thessaloniki International Fair.
Ask investors who have dealt with the country over the years and the stories are familiar: a tax changes, a regulatory framework shifts, an incentive looks different after money has already been committed.
The reputation is old enough to have become a cliché, but it is not merely anecdotal. A July 2026 Council of the European Union recommendation said frequent changes to tax rules, high compliance costs and regulatory barriers continue to raise costs for foreign investors in Greece.
After the financial crisis, we thought Greece might finally have learned how expensive that reputation could be.
The country had hit rock bottom, financially and in the confidence it commanded abroad. Recovery required more than balancing budgets. Greece had to persuade investors that long-term decisions could again be made within a reasonably stable policy environment.
At the beginning of September, we were finishing our Guide for Americans considering buying a home in Greece. We examined tax numbers, lawyers, engineers, title searches, closing costs, and the precautions buyers should take before committing their money.
The interest behind that guide is real, particularly among Greek Americans. Some are planning for retirement. Others want a place near relatives or a home their children can return to.
The assumption seemed straightforward: Greece welcomed that interest, provided buyers understood the rules.
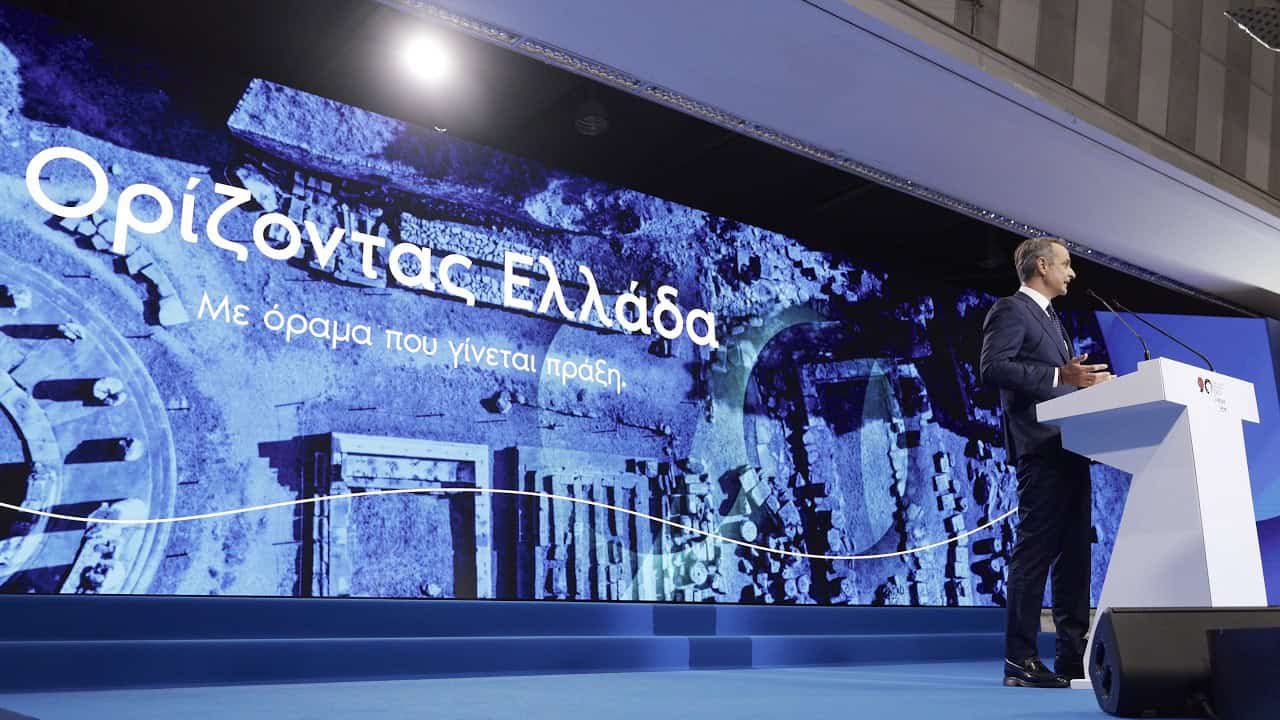
A few days later, Prime Minister Kyriakos Mitsotakis took the stage at the Thessaloniki International Fair and announced that Greece intends to raise the property transfer tax on residential purchases by many buyers from third countries from 3 percent to 15 percent. He called the measure an “αντικίνητρο,” a disincentive aimed at reducing foreign demand for housing.
We were surprised.
Not because governments cannot change taxes. Of course they can.
The question was what such a sharp change says about the durability of an investment policy Greece has spent years promoting.
The measure has not yet been enacted. Finance Minister Kyriakos Pierrakakis said it would take effect on July 1, 2027, and apply to individuals rather than legal entities. He also said the delayed start was intended not to “surprise the market.”
Including the municipal levy, the effective transfer-tax rate would rise from 3.09 percent to 15.45 percent, according to the government’s detailed breakdown of the TIF measures. On a taxable value of €500,000, that means €77,250 instead of €15,450.
There is a real problem behind the announcement.
Bank of Greece data show apartment prices rising 5.5 percent nationally in the second quarter of 2026 after increasing an average of 8.3 percent in 2025.
Foreign demand is not imaginary either. In the same government briefing, officials said buyers from outside the EU invested €1.217 billion in Greek real estate in 2025 and estimated that about €800 million went into housing.
That is substantial demand. It does not tell us how much third-country purchasing, by itself, has driven housing prices compared with limited supply, short-term rentals, tourism and years of weak residential construction. But the government is entitled to address it.
Nor is Greece unusual in doing so.
Ontario charges a 25 percent Non-Resident Speculation Tax on residential purchases involving foreign nationals, foreign corporations and certain trusts. Singapore imposes an additional 60 percent stamp duty on foreigners buying residential property and 65 percent on most entities. Australia currently generally restricts foreign persons from purchasing established homes while allowing exceptions tied to circumstances including investment that adds housing supply.
Those examples make it difficult to argue that Greece is uniquely hostile simply because it wants to curb foreign residential demand.
They also make the weakness in the Greek proposal clearer.
As currently announced, the higher Greek rate would apply to individuals but not legal entities. Yet a company buying the same existing apartment removes the same home from the market. If housing supply is the problem, that distinction needs an explanation.
The proposal also makes little distinction between someone buying one home for retirement and someone accumulating residential properties as investments.
Those are legitimate questions to answer before the measure becomes law.
There are places where the identity and ultimate control of a buyer can matter for entirely different reasons.
Thrace is one of them.
Greek law already subjects third-country acquisitions in designated border regions, including Xanthi, Rhodope and Evros, to special restrictions under Law 1892/1990. During a parliamentary debate in June over Turkish property purchases, Deputy Defense Minister Thanasis Davakis said 24 of 38 applications examined in Thrace had been rejected. The debate also raised concerns about restrictions potentially being bypassed through corporate structures.
If Greece has a national-security concern in a sensitive border region, identify the ultimate owners, close the loopholes and enforce the rules designed for that purpose.
That is a different policy problem from ordinary residential demand elsewhere in Greece.
There is another argument we are likely to hear about the 15 percent tax: in practice, it may not hurt as much as the headline suggests because Greece’s objective property values can be lower than actual market prices.
There is some truth in that.
But under the objective-value system, the transfer tax is based on the higher amount when the price stated in the contract exceeds the objective value, as AADE’s tax guidance explains.
Then there is the less comfortable argument: Greece has a history of property transactions in which the full real price was not declared.
That cannot seriously be offered as an answer to tax policy. The government itself moved against that practice by requiring property purchase prices to pass through banking channels. A contract recording payment in cash is invalid, and violations can carry substantial fines.
If the defense of a fivefold tax increase is that its effect may be softened through values or payments that fail to reflect the real transaction, the message to a legitimate investor becomes worse, not better.
Meanwhile, Greece continues to market itself abroad as a real-estate investment destination.
After MIPIM in Cannes this March, Enterprise Greece described the country as an investment “magnet” and a mature strategic real estate investment hub. On October 5, the agency opened Greece’s pavilion at EXPO REAL in Munich, where it said it would showcase “the breadth of investment opportunities available across the Greek real estate market.”
A resort development is obviously not the same as a private home purchase. Greece can encourage one type of capital and discourage another.
But changing direction still carries a cost.
Investors do not expect tax rates to remain frozen forever. They do look at whether changes follow a coherent policy, whether incentives last long enough to justify long-term decisions, and whether the country appears to know what kind of investment it wants.
The timing deserves notice too. Mitsotakis confirmed at his TIF press conference that general elections are expected in spring 2027.
That does not establish an electoral motive. Housing is a genuine concern, and governments are supposed to respond to voters.
But this was the final Thessaloniki International Fair before the expected election. A fivefold tax increase on many non-EU homebuyers can sound very different to a voter struggling with housing costs than to someone abroad deciding whether to commit money to Greece.
For the Diaspora, the contradiction is particularly uncomfortable.
Greece regularly encourages Greeks abroad to reconnect, return and invest. For many Greek Americans, “investment” is not a hotel or a factory. It is an apartment for retirement, a restored family property or a home their children can keep returning to.
Some hold Greek citizenship. Others do not. The final legislation will determine precisely who falls under the higher rate.
But a Greek American who has heard years of invitations to strengthen economic ties with Greece may reasonably ask what that invitation means when the terms can change this sharply.
The financial crisis taught Greece what lost confidence costs. Since then, the country has worked hard to persuade investors that the old uncertainty was behind it.
Greece has every right to protect access to housing, and other countries restrict foreign purchases far more aggressively. The question is whether this measure is coherent, whether it targets the problem it claims to solve, and whether its domestic benefit is worth the message it sends abroad.
Greece spent years asking investors to believe that the country had changed.
This proposal risks giving them a reason to ask whether it really has.